
Indexed Universal Life (IUL): Everything You Need to Know Before You Buy
If you've been researching Indexed Universal Life (IUL) insurance, you've probably come across conflicting opinions. Some people call it one of the most powerful financial tools available. Others call it a scam. The truth is much more nuanced.
At Veritas Legacy Partners, we believe every family deserves to understand how an IUL actually works before deciding whether it's the right fit. That's exactly what you'll find here. We'll walk you through the fundamentals, explain how cash value grows, address common misconceptions, and show you why the way an IUL is designed can be just as important as the insurance company behind it.
Are Indexed Universal Life (IUL) Policies a Scam?
No. But there are well-designed IULs, poorly designed IULs, and unfortunately, misleading sales presentations.
If you've spent any time researching Indexed Universal Life insurance online, you've probably seen completely opposite opinions. Some people say it's one of the most powerful financial tools available. Others insist it's a scam.
So who's right?
The truth is much simpler.
An Indexed Universal Life policy is a legitimate permanent life insurance product offered by established insurance companies and regulated by state insurance departments. It has helped families protect the people they love while providing the opportunity to build cash value over time.
So why does it receive so much criticism?
In our experience, the problem usually isn't the product itself. More often, it's the way the policy was designed, funded, explained, or recommended. Like any financial product, an IUL should be tailored to the individual's goals, budget, and long-term objectives. When that doesn't happen, disappointment often follows.
At Veritas Legacy Partners, we believe education comes before recommendations. Our goal is to help you understand how an IUL works, where it shines, where it has limitations, and whether it's the right fit for your situation. We believe an informed client will always make a better decision than one who feels pressured into buying a product they don't fully understand.
See Whether an IUL Is Right for You
Every family's goals are different. Before recommending any policy, we'll take the time to understand what you're trying to accomplish, answer your questions, and explain your options in plain English. Complete the short Coverage Review to get started. There's no cost, no obligation, and absolutely no pressure.
What Is an Indexed Universal Life (IUL) Policy?
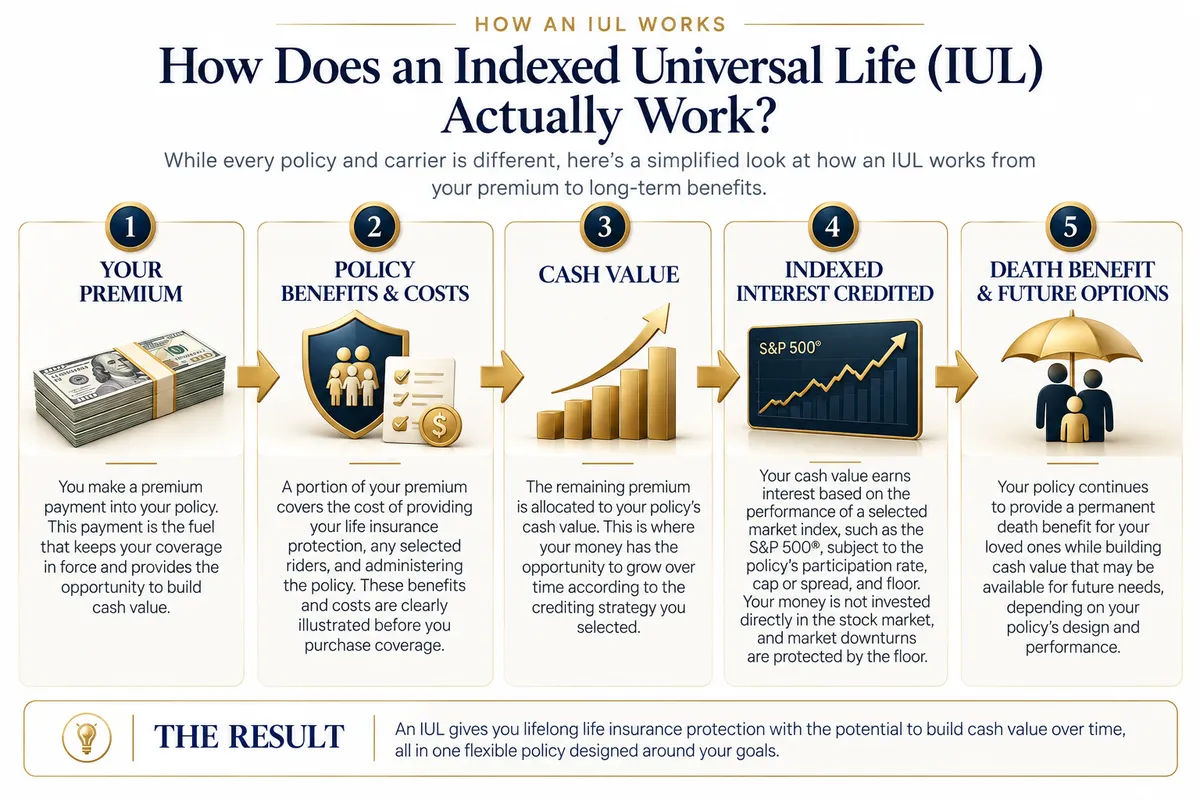
An Indexed Universal Life (IUL) policy is a type of permanent life insurance designed to provide lifelong protection while also giving your policy the opportunity to build cash value over time.
Unlike term life insurance, which provides coverage for a specific number of years, an IUL is designed to remain in force for your lifetime, provided the policy is properly funded and maintained according to its terms.
What makes an IUL different from many other types of life insurance is the way the cash value has the potential to grow. Instead of earning a fixed interest rate every year, the policy credits interest based on the performance of a market index, such as the S&P 500®, while following the rules and crediting methods established by the insurance company.
It's also important to understand what an IUL is not.
Your money is not invested directly in the stock market. Instead, the insurance company uses a crediting strategy tied to the performance of a selected market index. That means your cash value has the opportunity to benefit when the selected index performs well, while policy floors help protect against receiving negative indexed interest during market downturns.
At its core, an Indexed Universal Life policy combines three primary benefits into one financial tool:
A permanent death benefit to help protect the people you love.
Cash value growth potential that can accumulate over time.
Flexible policy features that may allow the policy to adapt as your financial goals change.
Like any financial product, however, an IUL is only as effective as the way it's designed. That's why understanding how it works is just as important as understanding what it is.
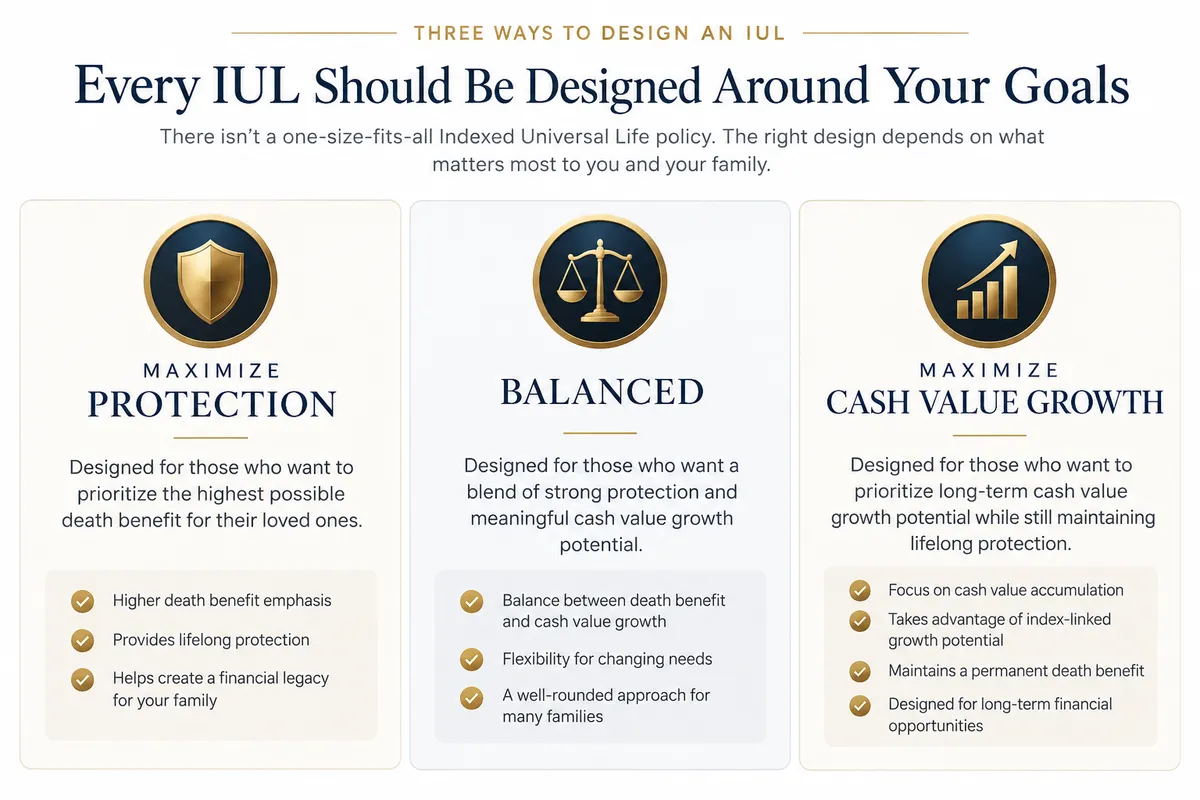
There isn't a one-size-fits-all Indexed Universal Life policy. Some people want to maximize protection for their family. Others want a balance between protection and long-term cash value growth. Others prioritize maximizing cash value potential. The right design starts with understanding your goals, not forcing everyone into the same policy.
Ready to See What an IUL Could Look Like for You?
Every Indexed Universal Life policy should be designed around your goals, not a one-size-fits-all approach. We'll walk you through your options, answer your questions, and prepare a personalized illustration based on what you're trying to accomplish.
Why Do Some People Love IULs While Others Say They're Terrible?
Why Are Opinions About IULs So Different?
If you've researched Indexed Universal Life insurance online, you've probably noticed something surprising. One person says it's one of the best financial tools ever created, while another says they would never own one.
How can the opinions be so different?
The answer is that not every IUL is designed the same.
Two policies can come from different insurance companies, use different indexing strategies, have different participation rates, different policy charges, different funding strategies, and completely different long-term objectives. Even two policies from the same insurance company can perform very differently depending on how they're designed.
Unfortunately, many people judge every IUL based on a single experience or a policy that wasn't the right fit for their needs. That's like saying every vehicle is the same because you drove one you didn't like.
At Veritas Legacy Partners, we believe the conversation shouldn't start with "Which company is best?"
It should start with "What are you trying to accomplish?"
Once that question is answered, the policy can be designed around your goals instead of forcing your goals to fit a generic policy.
Can I Lose Money in an IUL?
An Indexed Universal Life (IUL) policy is designed to protect your policy's cash value from negative indexed interest when the market has a down year. Depending on the policy and the crediting strategy you select, many IULs include a floor that prevents negative indexed interest from being credited.
It's important to understand that an IUL is still a life insurance policy. Policy charges, the cost of insurance, loans, withdrawals, and the way the policy is funded all affect long-term performance. A properly designed and appropriately funded policy is one of the most important factors in helping an IUL meet its intended purpose. That's why policy design matters just as much as the insurance company behind it.
How Can My Money Grow in an IUL?
The cash value in an Indexed Universal Life policy has the opportunity to earn interest based on the performance of a market index, such as the S&P 500®, subject to the policy's crediting method, participation rate, cap, spread, or other policy provisions.
Your money is not invested directly in the stock market. Instead, the insurance company credits interest to your policy based on the terms of your selected indexing strategy. When designed properly and funded consistently, an IUL can provide long-term cash value growth potential while continuing to provide permanent life insurance protection.
What's the Difference Between a Capped and Uncapped IUL?
A capped IUL limits the maximum amount of indexed interest that can be credited during a given crediting period. For example, if the selected index performs above the policy's cap, the credited interest is limited to that cap.
An uncapped IUL does not use a traditional cap on indexed interest. Instead, the amount of interest credited is determined by other factors outlined in the policy, such as the participation rate or spread, depending on the crediting strategy offered by the insurance company.
Neither approach is automatically better than the other. The right choice depends on your financial goals, risk preferences, funding strategy, and the specific policy being considered. At Veritas Legacy Partners, we compare multiple carriers and policy designs to help determine which approach best fits your objectives.
What Is a Participation Rate?
A participation rate determines how much of an index's positive performance is used when calculating the indexed interest credited to your policy. For example, a 100% participation rate means the policy uses 100% of the index's gain, subject to any applicable cap, spread, or other policy provisions. Some strategies may offer participation rates above 100%, while others may be lower.
Participation rates are only one part of an IUL's design. They should always be considered alongside other features such as caps, spreads, policy charges, and your overall financial goals.
Can I Access My Cash Value While I'm Alive?
Yes. One of the features of an Indexed Universal Life policy is the ability to access available cash value during your lifetime through policy loans or withdrawals, subject to the terms of the policy. It's important to understand that loans and withdrawals will generally reduce the policy's cash value and death benefit and may have tax consequences if the policy lapses or does not remain in force. Before taking money from your policy, it's important to understand how it may affect your long-term objectives.
Can an IUL Provide Tax-Advantaged Retirement Income?
Many people use an Indexed Universal Life policy as part of their long-term retirement strategy because, when structured appropriately and kept in force, policy loans may provide access to cash value on a tax-advantaged basis under current federal tax law.
An IUL should not be viewed as a replacement for every retirement account. Instead, it may serve as one component of a broader financial strategy, depending on your individual goals and circumstances. We recommend discussing tax-related questions with a qualified tax professional.
How Long Should I Plan to Keep an IUL?
An Indexed Universal Life policy is generally intended as a long-term financial strategy rather than a short-term investment. Building meaningful cash value takes time, and many of the benefits associated with an IUL become more significant over the long term.
Because every situation is different, the ideal funding period and long-term strategy should be based on your financial goals, budget, and how you plan to use the policy throughout your lifetime.
Can I Purchase an IUL for My Child or Grandchild?
Yes. Many parents and grandparents purchase Indexed Universal Life policies for children to provide permanent life insurance coverage while giving the policy years or even decades to build cash value.
When properly designed and funded, starting at a young age can provide flexibility later in life. Every family's situation is different, so the appropriate policy design should be based on the goals you hope to accomplish for your child or grandchild.
Is an IUL Right for Everyone?
No. While an Indexed Universal Life policy can be an excellent solution for many people, it isn't the right fit for every situation.
The best financial strategy depends on your goals, budget, time horizon, and overall financial picture. In some cases, another type of life insurance or financial product may better meet your needs. That's why we believe education and personalized recommendations are more important than trying to fit everyone into the same solution.
How Do I Know if an IUL Is Right for Me?
The best way to determine whether an Indexed Universal Life policy is right for you is to start with a conversation about your goals.
At Veritas Legacy Partners, we take the time to understand what you're trying to accomplish before recommending any policy. We'll answer your questions, explain your options in plain English, and prepare a personalized illustration so you can make an informed decision with confidence. There is no cost and no obligation to see whether an IUL is the right fit for your situation.
Why Should I Choose Veritas Legacy Partners?
Choosing an Indexed Universal Life policy isn't just about selecting an insurance company. It's about working with someone who takes the time to understand your goals and helps you design a policy that fits your needs.
At Veritas Legacy Partners, we believe education comes before recommendations. Our job isn't to sell you a policy. Our job is to help you understand your options so you can make an informed decision with confidence.
When you work with Veritas Legacy Partners, you can expect:
✔ An independent insurance brokerage representing multiple A-rated and A+ rated insurance carriers.
✔ A personalized policy design based on your financial goals, budget, and long-term objectives.
✔ Clear, straightforward explanations without high-pressure sales tactics or confusing insurance jargon.
✔ A personalized IUL illustration so you can see how different policy designs may align with your objectives before making a decision.
✔ Ongoing service and policy reviews as your life, family, and financial goals evolve.
Whether you're looking to protect your family, build long-term cash value, supplement retirement income, or leave a financial legacy, our goal is to help you understand your options and design a solution that's built around you.
Ready to See How an IUL Could Be Designed for You?
Every family has different goals, priorities, and financial circumstances. That's why every Indexed Universal Life policy should begin with a conversation, not a quote.
We'll take the time to understand what you're trying to accomplish, answer your questions, and prepare a personalized illustration based on your goals. You'll see exactly how the policy is designed, how it works, and whether it's the right fit for your situation before making any decisions.
There is no cost, no obligation, and absolutely no pressure. Just honest guidance to help you make an informed decision.

“Trust in the Lord with all your heart and lean not on your own understanding;
in all your ways submit to Him, and He will make your paths straight.”
— Proverbs 3:5–6
“But as for me and my household, we will serve the Lord.”
— Joshua 24:15
Copyright 2026.© Veritas Legacy Partners. All rights reserved.
Joshua Edmund – Licensed Insurance Producer (NH., MA., ME., TX. SC.)
NPN: 22132805
Important Information: Indexed Universal Life (IUL) insurance is a permanent life insurance product. Policy values, credited interest, policy charges, loans, withdrawals, and other features vary by carrier and policy design. The information on this page is provided for educational purposes only and is not a policy illustration, guarantee of future performance, or individualized financial, tax, or legal advice. Any recommendation should be based on your personal goals, financial situation, and an individual policy review.
Insurance products are offered through Veritas Legacy Partners. Coverage availability and terms may vary by state and carrier. This is not a guarantee of coverage or pricing.